
Midlife Squeeze: Supporting Children and Aging Parents Strains Finances
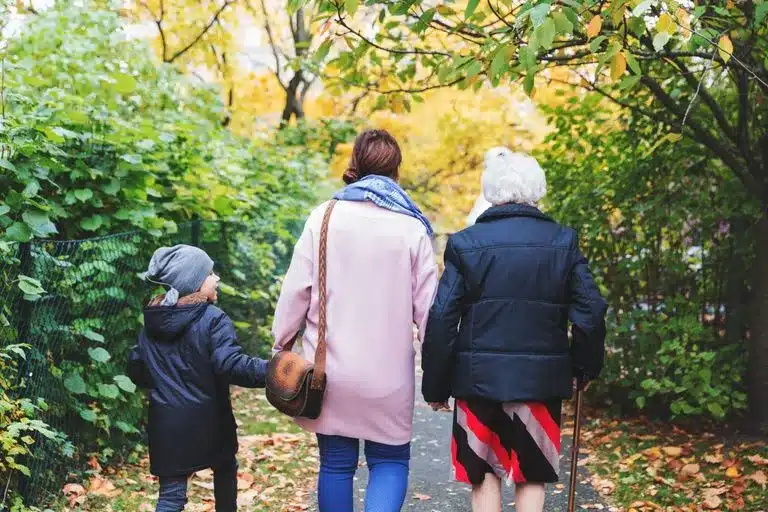
Many individuals in midlife anticipate a period of greater financial freedom and personal focus after years of career building and family raising. However, a growing demographic finds themselves unexpectedly shouldering the dual responsibilities of supporting both their children and aging parents. This ‘sandwich generation’ often faces significant financial and emotional pressure.
Generational Demands and Shifting Economic Realities
Adults in this demographic, frequently belonging to Generation X (born between 1965 and 1980), are commonly providing care, practical assistance, and financial aid to elderly relatives. Simultaneously, they are supporting children who remain dependent for longer than previous generations, often due to challenges in securing affordable housing or stable employment.
Economic factors such as rising rents, high property values, and an increased cost of living mean many parents continue to offer support well into their children’s twenties and thirties. Data from the Office for National Statistics (ONS) indicates that in 2025, 35% of men aged 20 to 34 were living with their parents, compared to 22% of women in the same age bracket. Concurrently, increased life expectancy means aging parents may require care and financial assistance for extended periods. ONS projections estimate life expectancy at birth to be approximately 83.8 years for women and 80 years for men.
Retirement Savings at Risk for Generation X
The financial demands of supporting two generations can significantly hinder long-term financial planning, particularly retirement savings. A recent analysis by the Pension Commission highlights Generation X as particularly vulnerable to insufficient retirement provisions. This vulnerability stems not only from the pressures of caring for both younger and older generations but also from missing out on generous final salary pension schemes and being too old to fully benefit from automatic workplace pension enrollment introduced in 2012.
Rebecca Williams, financial planning divisional lead at Rathbones, observes, “Many Gen Xers are sleepwalking into retirement with far less financial security than their parents. They came of age as defined benefit pensions were disappearing and have since faced years of stagnant wage growth and repeated financial shocks, making it harder to build robust, long-term savings.” She adds, “This cohort also represents a large part of the sandwich generation, juggling day-to-day costs while supporting both ageing parents and children. As a result, boosting retirement savings can be difficult amid ongoing financial pressures.”
Further analysis from PensionBee reveals that individuals over 50 often possess significantly smaller pension pots than needed. On average, women in this age group hold £30,644, while men hold £54,512.
Strategies for Navigating Financial Pressures
Seek Available Financial Support
Individuals providing unpaid care for at least 35 hours per week may qualify for Carer’s Allowance, currently valued at £86.45 weekly. Eligibility for this allowance is not affected by personal savings, though income may be a factor. It is also advisable to verify that elderly relatives are receiving all entitled benefits, such as Attendance Allowance or Pension Credit.
Safeguard Retirement Savings
While the inclination to reduce pension contributions or access savings to assist family members is understandable, doing so can have long-term consequences. Reduced pension contributions not only diminish personal savings but can also mean forfeiting valuable employer contributions and years of potential investment growth.
Discuss Lasting Power of Attorney
Initiating conversations with aging parents about Lasting Power of Attorney (LPA) is crucial. An LPA empowers individuals to designate trusted people to manage their affairs if they lose mental capacity in the future. Separate LPAs exist for property and financial matters, and for health and welfare decisions. Establishing an LPA does not relinquish a parent’s control; rather, it ensures that trusted individuals can act on their behalf without undue legal delays should future decisions be necessary and the individual is unable to make them.
Prioritize Personal Wellbeing
When managing the care of multiple generations, personal wellbeing can easily be overlooked. It is vital to allocate regular time for enjoyable activities, whether it be exercise, social gatherings, volunteering, or pursuing hobbies. Even a few hours per week dedicated to personal interests can significantly reduce stress and prevent burnout.
Essential Checklist for Supporting Multiple Generations:
- Investigate eligibility for Carer’s Allowance and other potential financial aid.
- Confirm that elderly relatives are claiming all applicable benefits.
- Maintain pension contributions and avoid depleting retirement savings if possible.
- Discuss and establish Lasting Power of Attorney with aging parents before a crisis arises.
- Develop a household budget to track all expenditures.
- Engage in open dialogue with adult children regarding financial expectations and future independence.
- Consult a professional financial advisor if balancing competing financial priorities proves challenging.
- Ensure regular time is dedicated to personal health and wellbeing.
