
Samsung Electronics’ stock experienced a reversal on Thursday, shedding early gains that followed the U.S. Federal Reserve’s latest interest rate decision. This pullback highlights a divergence between cautious global investors, concerned about macroeconomic factors, and some financial analysts who remain optimistic about the semiconductor giant’s future earnings potential, largely driven by the burgeoning memory market.
The stock had initially climbed following the Fed’s announcement of a 25-basis-point rate hike, reaching a high of 259,000 won before retreating towards the previous day’s closing price of 253,500 won. This volatility underscores the market’s sensitivity to broader economic conditions, particularly rising interest rates, which can impact the valuation of technology stocks.
Goldman Sachs Maintains Bullish Stance on Samsung
Despite the stock’s intraday decline and prevailing macroeconomic headwinds, investment bank Goldman Sachs has reiterated its ‘Buy’ rating on Samsung Electronics, setting an ambitious price target of 490,000 won. This target implies a potential upside of approximately 93% from recent trading levels.
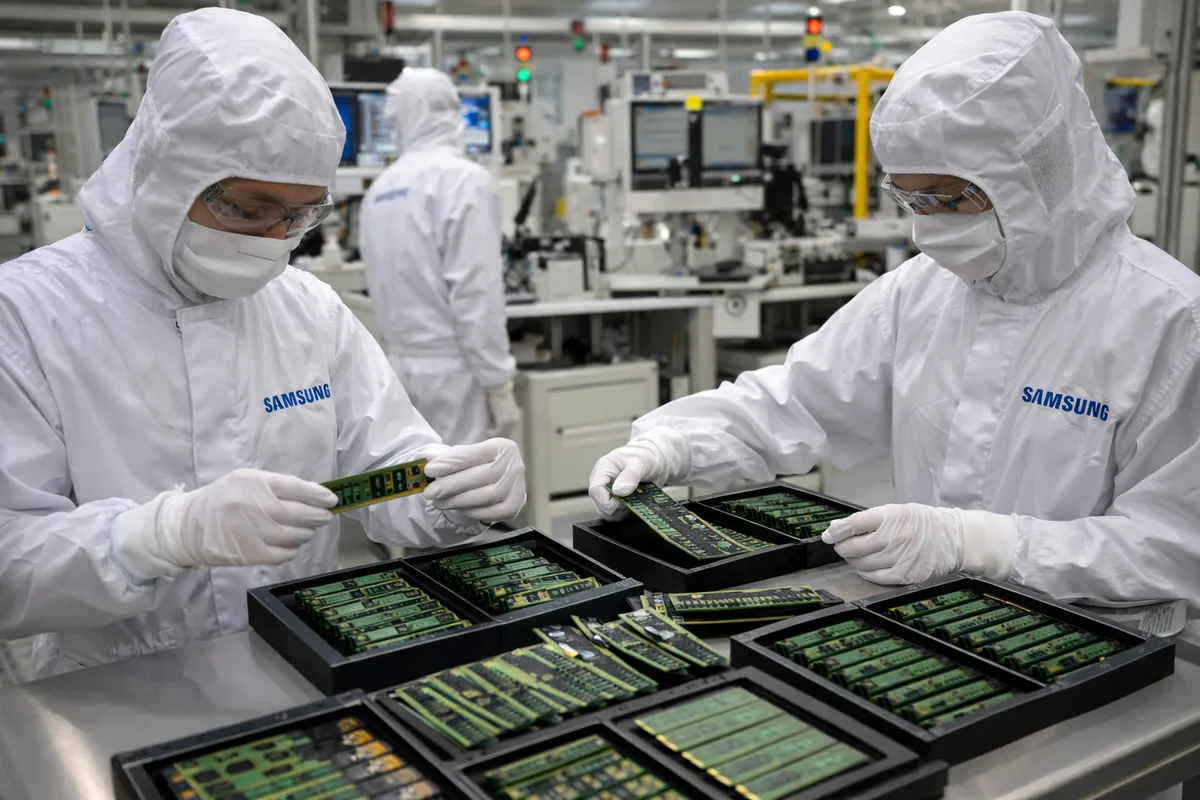
Goldman Sachs’ optimistic outlook is primarily anchored in its projections for the memory market, specifically for DRAM and NAND flash memory. The firm anticipates a sequential increase of around 20% in average selling prices (ASPs) for these products in the third quarter. Furthermore, Goldman Sachs forecasts a significant surge of approximately 100% in High Bandwidth Memory (HBM) ASPs for the upcoming year, attributing this to persistently tight supply conditions and robust demand from the artificial intelligence (AI) sector.
The core of Goldman Sachs’ investment thesis rests on the belief that the current market pressure on Samsung’s stock is more a reflection of “macro fear” and discount rate concerns rather than a fundamental collapse in demand for its products. The firm suggests investors are being presented with an opportunity to buy into the stock at a discount, bridging the gap between broader economic anxieties and the anticipated acceleration in memory chip earnings.
Key Risks to Goldman Sachs’ Outlook
However, Goldman Sachs acknowledges significant risks that could impede its projected upside. The primary concern is the potential for memory pricing momentum to falter. If DRAM and NAND ASPs fail to meet the firm’s expectations, or if HBM ASP growth stalls, the higher interest rate environment could exert permanent downward pressure on Samsung’s valuation. The firm also noted that SK Hynix, a competitor in the memory market, shares similar upside potential, provided HBM supply remains constrained and AI infrastructure demand continues to grow strongly.
Divergent Views on the Memory Market
Not all analysts share Goldman Sachs’ ebullient view on the memory sector. BNK Investment & Securities, for instance, has adopted a more cautious stance, downgrading Samsung to a ‘Hold’ rating and lowering its price target to 270,000 won from a previous 300,000 won.
BNK Investment & Securities analyst Lee Min-hee has expressed concerns that the memory price rally may be nearing its peak. The firm points to an accelerating expansion in chip supply, which could lead to a less favorable supply-demand balance. Additionally, BNK suggests that demand elasticity is weakening, implying that customers may become more sensitive to price increases, potentially capping further ASP growth.
This contrasting perspective highlights a critical debate in the market: whether the current memory upcycle, particularly driven by AI demand for HBM, has further room to run or if supply-side adjustments are poised to temper price increases. The significant discrepancy between Goldman Sachs’ 490,000 won target and BNK’s 270,000 won target underscores the uncertainty surrounding the future trajectory of memory chip pricing and Samsung’s profitability.
Factors Influencing Samsung’s Valuation
The market’s reaction to the Federal Reserve’s rate hike underscores the sensitivity of technology stocks to interest rate movements. Higher long-term yields, such as the elevated U.S. 10-year Treasury yield, increase the discount rate applied to future earnings, thereby reducing the present value of those earnings. This effect can depress stock valuations, even when a company’s underlying business fundamentals remain strong.
Furthermore, rising interest rates can lead to tighter global liquidity, potentially discouraging foreign investment in emerging markets like South Korea. Evidence of this can be seen in foreign investors’ selling activity in Samsung shares during September, even on days when the stock experienced gains.
Looking Ahead: Key Catalysts for Samsung
Samsung’s stock performance in the coming months will likely hinge on several key factors:
- Memory Pricing Trends: Continued sequential increases in DRAM and NAND ASPs, alongside sustained growth in HBM prices, will be crucial for validating the bullish outlook.
- HBM Supply-Demand Dynamics: The balance between HBM production capacity and the insatiable demand from AI applications will dictate future pricing power. Any significant easing of supply constraints or a slowdown in AI infrastructure build-out could negatively impact HBM ASPs.
- Macroeconomic Environment: The trajectory of global interest rates and inflation will continue to influence investor sentiment and the overall valuation of technology stocks.
- Third-Quarter Earnings: Upcoming earnings reports will provide concrete data on the company’s performance and offer insights into the ongoing memory cycle.
The tension between macroeconomic concerns and the specific growth drivers within the semiconductor industry, particularly the AI-fueled demand for advanced memory solutions, presents a complex investment landscape for Samsung Electronics. While analysts like those at Goldman Sachs see substantial upside driven by memory market dynamics, others caution that broader economic pressures and supply-side developments could limit future gains.
